The 50/30/20 Rule for Indian Salaried Employees: A Simple Way to Manage Your Money
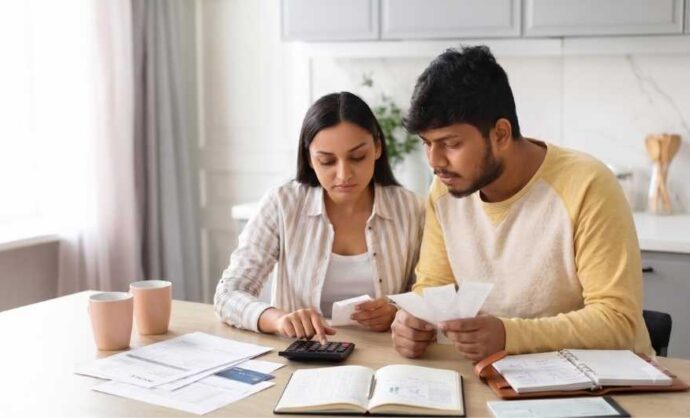
Ever wondered where your salary disappears every month?
You receive your paycheck, pay a few bills, order food a couple of times, maybe buy something online, and before you know it, you’re counting the days until the next salary credit.
If this sounds familiar, you’re not alone.
Managing money can feel overwhelming, especially when you’re balancing rent, bills, family responsibilities, savings goals, and the occasional desire to treat yourself. That’s where the 50/30/20 rule comes in.
It’s one of the simplest budgeting methods in the world because it doesn’t require complicated spreadsheets, financial expertise, or hours of planning. It simply helps you divide your income into three categories and spend with intention.
Let’s understand how it works and how Indian salaried employees can use it effectively.
What Is the 50/30/20 Rule?
The 50/30/20 rule was popularized by Elizabeth Warren and Amelia Warren Tyagi in their book All Your Worth.
The idea is simple:
- 50% of your take home salary goes toward needs.
- 30% goes toward wants.
- 20% goes toward savings and investments.
Think of your salary as three buckets.
The first bucket helps you live today, the second bucket helps you enjoy today, the third bucket helps you secure tomorrow and that’s the entire philosophy behind the rule.
First Things First: Use Your Take Home Salary
One of the most common budgeting mistakes is planning expenses based on your CTC or gross salary.
The 50/30/20 rule should always be applied to the amount that actually reaches your bank account after deductions.
For salaried employees in India, deductions may include:
- Income tax or TDS
- Employee Provident Fund (EPF)
- Professional tax (where applicable)
For example, if your gross monthly salary is ₹50,000, your take home salary may be around ₹45,000–₹47,000 depending on deductions.
Your budget should be based on this take home amount, not the salary mentioned in your offer letter.
Understanding The Three Buckets
Bucket 1: Needs (50%)
Needs are expenses you cannot reasonably avoid.
A simple question can help identify them:
“If I stop paying for this today, will it create a serious problem?”
If the answer is yes, it probably belongs in the needs category.
Examples include:
- House rent
- Home loan or personal loan EMI
- Groceries
- Electricity and water bills
- Mobile and internet bills
- Essential transportation
- Health insurance premiums
- Children’s education expenses
Let’s say your monthly take home salary is ₹40,000.
According to the rule, around ₹20,000 should ideally cover your essential expenses.
Of course, real life isn’t always perfect. If your rent alone consumes a large portion of your income, don’t panic. The rule is a guideline, not a strict law.
The goal is awareness, not perfection.
Bucket 2: Wants (30%)
Wants are expenses that make life enjoyable but aren’t necessary for survival.
These are the things you choose rather than need.
Examples include:
- Dining out
- Streaming subscriptions
- Vacations
- Shopping
- Entertainment
- Hobbies
- Premium gadgets
- Weekend outings
A useful test is:
“Can I live without this for a month?”
If the answer is yes, it’s probably a want.
That doesn’t mean you should eliminate all wants.
In fact, budgeting some money for enjoyment helps you stick to your financial plan in the long run. A budget that feels like punishment rarely lasts.
Bucket 3: Savings and Investments (20%)
This bucket is dedicated to your future.
The money allocated here can be used for:
- Building an emergency fund
- Mutual fund SIPs
- Public Provident Fund (PPF)
- National Pension System (NPS)
- Fixed deposits
- Retirement planning
- Long-term financial goals
Many people wait until the end of the month to save whatever is left.
Unfortunately, very little is usually left.
Instead, consider saving first and spending later.
The moment your salary arrives, transfer the savings portion to a separate account or investment.
This approach is often called “Pay Yourself First,” and it can make a huge difference over time.
A Simple Example
Suppose your monthly take home salary is ₹50,000.
Your budget could look something like this:
Needs (50%) – ₹25,000
- Rent
- Utilities
- Groceries
- Transportation
- Insurance
Wants (30%) – ₹15,000
- Eating out
- Shopping
- Entertainment
- Travel
Savings & Investments (20%) – ₹10,000
- SIPs
- Emergency fund
- Retirement savings
This structure gives every rupee a purpose before it gets spent.
What If You Live in an Expensive City?
Many professionals in cities like Mumbai, Bengaluru, Delhi, Pune, and Hyderabad face a common challenge: housing costs.
Rent can easily consume 35%- 45% of take home income.
In such situations, a strict 50/30/20 split may not be realistic.
That’s perfectly normal.
For example, if your take-home salary is ₹60,000 and your rent is ₹25,000, your needs category will naturally exceed 50%.
Instead of abandoning budgeting altogether, adjust the percentages temporarily.
You might follow:
- 60% Needs
- 20% Wants
- 20% Savings
Or:
- 55% Needs
- 25% Wants
- 20% Savings
The principle remains the same: spend consciously and continue saving whenever possible.
What If Your Salary Is Low?
Many people believe budgeting only works when income is high.
That’s not true.
In fact, budgeting becomes even more important when money is limited.
If your monthly take home salary is ₹15,000, saving 20% may seem difficult.
Start with what you can.
Even saving ₹1,000 or ₹1,500 every month builds a habit that becomes powerful over time.
Financial progress is often less about the amount and more about consistency.
Don’t Ignore Your Emergency Fund
Think of an emergency fund as a financial safety net.
You hope you never need it, but you’ll be glad it’s there when life throws an unexpected challenge your way.
Medical emergencies, sudden travel requirements, job loss, or urgent repairs can happen without warning.
A good starting goal is to build an emergency fund that covers three to six months of essential expenses.
Keep this money in a place that is safe and easily accessible.
Common Mistakes to Avoid
1. Budgeting Based on Gross Salary
Always use your take-home income.
2. Treating Wants as Needs
A premium smartphone upgrade may feel essential, but it usually isn’t.
Be honest about the difference.
3. Saving Whatever Is Left
Save first, spend later.
4. Ignoring Lifestyle Inflation
As income increases, spending often increases too.
Try to increase your savings rate whenever you receive a raise instead of upgrading every aspect of your lifestyle.
5. Being Too Rigid
Some months won’t go according to plan.
Unexpected expenses happen.
The goal is progress, not perfection.
Final Thoughts
The 50/30/20 rule isn’t a magic formula that will instantly make you wealthy.
What it does offer is something equally valuable: clarity.
Instead of wondering where your money went, you’ll know exactly where it’s going.
Whether you’re earning ₹15,000 a month or ₹1,00,000, the principle remains the same: spend responsibly, enjoy life within limits, and consistently save for the future.
Personal finance doesn’t have to be complicated.
Sometimes, all it takes is dividing your salary into three simple buckets and sticking to the plan.
Categories
Tags
Quick Links
Prolend© 2026 All Rights Reserved.